Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
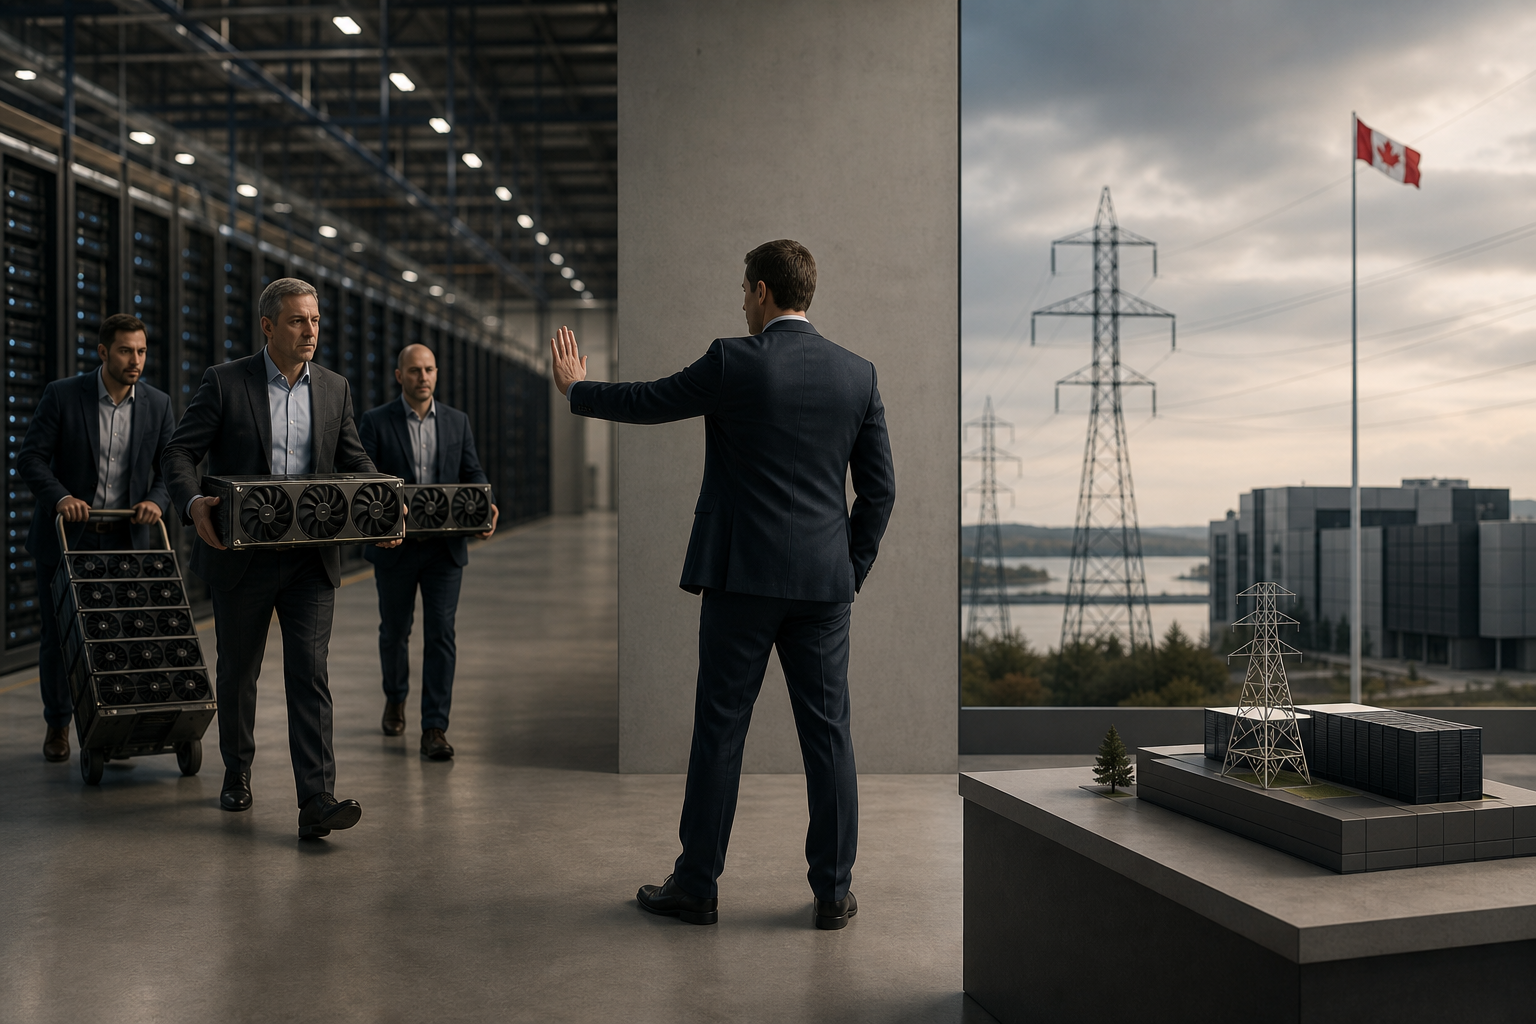
A $500-million loan secured against a warehouse full of Nvidia H100 chips sounds safe until the lender learns those chips have a four-to-five-year useful life and the newest generation just shipped. Fortress Investment Group is telling private credit funds that collateral built for AI training is a wasting asset, and too many lenders are writing cheques they can't afford to eat.
The warning lands at a moment when private credit, now a $1.7-trillion global market, is scrambling to deploy capital into anything carrying the words "artificial intelligence." Traditional banks won't touch most of these deals. Regulatory capital rules make lending against depreciating tech hardware unattractive, especially when the borrower is burning cash on compute with no clear path to revenue. That creates an opening, and non-bank lenders have charged through it.
The collateral isn't what it looks like
The mispricing starts with how the asset is classified. Roads, bridges, and power plants hold value over decades. A data centre full of GPUs does not. Fortress notes that specialized AI hardware, particularly the high-end chips used for large-scale model training, faces obsolescence risk that dwarfs anything in conventional lending on roads, bridges, and power plants.
When a more energy-efficient chip enters the market, the previous generation doesn't depreciate gracefully. It collapses. Inference workloads, running established models rather than training new ones, may provide some residual demand, but the pricing power vanishes. A lender holding a first lien on last year's hardware discovers that "market value" is whatever a distressed equipment broker will pay, and that number tends toward zero faster than the loan amortizes.
Energy access matters more than the hardware itself. In Ontario, the Independent Electricity System Operator controls grid capacity, and new data centres require approvals that can take years. A borrower with chips and no power allocation is effectively holding inventory it cannot deploy. Underwriters who skip this check are lending against a bottleneck where no power flows in.
The government backstop that isn't there
Canada's $2.4-billion federal commitment to AI hardware has created a false sense of security. Lenders are pricing in an implicit sovereign guarantee: the logic that Ottawa will step in to protect "critical" AI projects if things go sideways. That assumption doesn't survive contact with how bailouts actually work. Governments rescue systemically important institutions, not individual creditors holding bad paper on speculative hardware.
The "Sovereign AI" push, the idea that Canada needs domestic compute capacity independent of U.S. cloud providers, is real policy. When a private lender finances a data centre that runs out of cash before it signs its first customer, the federal government's interest in national AI capacity does not translate into a cheque to the lender. The hardware gets sold at salvage. The loan gets written off.
What disciplined underwriting looks like
The alternative to FOMO isn't rejecting AI deals outright. It's requiring the same cash-flow coverage that works in every other sector. Fortress points to a widening divide between lenders who underwrite to balance sheets and those who underwrite to narratives. The former require debt-service coverage ratios above 1.25x, validate power contracts before closing, and haircut collateral values to reflect depreciation. The latter are betting that being early to the AI wave matters more than loan performance.
For lenders based in Toronto or Ottawa in regions with genuine AI research concentrations, the pressure to support local startups makes it tempting to lower standards. Invest Ottawa and the Kanata North tech corridor are full of startups moving from venture capital to venture debt to avoid dilution. That's fine when the debt is sized to the business. It becomes a problem when the loan is sized to the hype.
The winner-takes-all defence holds only if you pick the winner. Most lenders won't.


A $500-million loan secured against a warehouse full of Nvidia H100 chips sounds safe until the lender learns those chips have a four-to-five-year useful life and the newest generation just shipped. Fortress Investment Group is telling private credit funds that collateral built for AI training is a wasting asset, and too many lenders are writing cheques they can't afford to eat.
The warning lands at a moment when private credit, now a $1.7-trillion global market, is scrambling to deploy capital into anything carrying the words "artificial intelligence." Traditional banks won't touch most of these deals. Regulatory capital rules make lending against depreciating tech hardware unattractive, especially when the borrower is burning cash on compute with no clear path to revenue. That creates an opening, and non-bank lenders have charged through it.
The collateral isn't what it looks like
The mispricing starts with how the asset is classified. Roads, bridges, and power plants hold value over decades. A data centre full of GPUs does not. Fortress notes that specialized AI hardware, particularly the high-end chips used for large-scale model training, faces obsolescence risk that dwarfs anything in conventional lending on roads, bridges, and power plants.
When a more energy-efficient chip enters the market, the previous generation doesn't depreciate gracefully. It collapses. Inference workloads, running established models rather than training new ones, may provide some residual demand, but the pricing power vanishes. A lender holding a first lien on last year's hardware discovers that "market value" is whatever a distressed equipment broker will pay, and that number tends toward zero faster than the loan amortizes.
Energy access matters more than the hardware itself. In Ontario, the Independent Electricity System Operator controls grid capacity, and new data centres require approvals that can take years. A borrower with chips and no power allocation is effectively holding inventory it cannot deploy. Underwriters who skip this check are lending against a bottleneck where no power flows in.
The government backstop that isn't there
Canada's $2.4-billion federal commitment to AI hardware has created a false sense of security. Lenders are pricing in an implicit sovereign guarantee: the logic that Ottawa will step in to protect "critical" AI projects if things go sideways. That assumption doesn't survive contact with how bailouts actually work. Governments rescue systemically important institutions, not individual creditors holding bad paper on speculative hardware.
The "Sovereign AI" push, the idea that Canada needs domestic compute capacity independent of U.S. cloud providers, is real policy. When a private lender finances a data centre that runs out of cash before it signs its first customer, the federal government's interest in national AI capacity does not translate into a cheque to the lender. The hardware gets sold at salvage. The loan gets written off.
What disciplined underwriting looks like
The alternative to FOMO isn't rejecting AI deals outright. It's requiring the same cash-flow coverage that works in every other sector. Fortress points to a widening divide between lenders who underwrite to balance sheets and those who underwrite to narratives. The former require debt-service coverage ratios above 1.25x, validate power contracts before closing, and haircut collateral values to reflect depreciation. The latter are betting that being early to the AI wave matters more than loan performance.
For lenders based in Toronto or Ottawa in regions with genuine AI research concentrations, the pressure to support local startups makes it tempting to lower standards. Invest Ottawa and the Kanata North tech corridor are full of startups moving from venture capital to venture debt to avoid dilution. That's fine when the debt is sized to the business. It becomes a problem when the loan is sized to the hype.
The winner-takes-all defence holds only if you pick the winner. Most lenders won't.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It
Defense Stocks Slide as Investors Price In Midterm Funding Gridlock